Anchorage Mortgage Broker - Slavik Lund
start today. own tomorrow.
hey, i'm slavik
NMLS# 2054568
Slavik Lund is an Anchorage, Alaska mortgage broker with First Rate Financial, helping veterans, first-time homebuyers and real estate investors buy, refinance and build wealth through real estate across Alaska.
When should you start the process?
Getting pre-approved early gives you the opportunity to plan, and planning is key. It allows you to work with me to come up with both a monthly budget and a budget for a down-payment that fits your short & long term goals.
Even the well-qualified can benefit from some advance planning and structuring. The worst thing to do is to rush the pre-approval process. There are lots of things in life you can get away with leaving to the last minute, your home financing and planning shouldn't be one of them.
Planning to Use a VA Loan? The JBER VA Loan Guide
meet slavik.
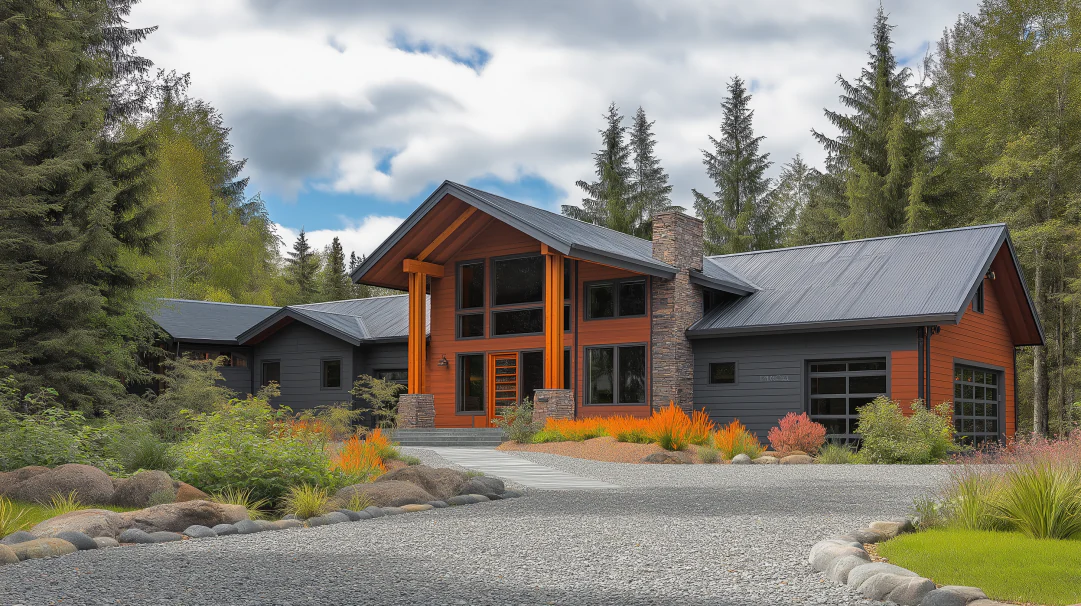
I'm a mortgage broker, real estate investor, and educator based in Anchorage. My work is centered around a simple idea most people overlook until it's too late:
the way you structure your life financially will either give you options or quietly take them away.
I bought my first fourplex at 20 and built from there. That experience changed how I see real estate. A property is not just a place to live. It's a decision point. It can either anchor you to higher expenses and less flexibility, or it can lower your cost of living, produce income, and buy back your time.
Most people follow the default path, make isolated decisions, and hope it works out. I help you zoom out and see the full picture and think in terms of leverage, sequencing, and long term alignment so each move builds on the last.
Outside of lending, I create content around passive income, real estate, and becoming the main character of your life. If you understand the game, you can play it on purpose. At home, I'm a husband and a father of three young boys (third is due December 2026). With kids I've recently learned that time matters more, decisions compound further and the margin for drifting gets smaller. These concepts shape everything I build.
Assets should buy your lifestyle not the other way around. (more on youtube)
follow me on social
see if you’re in a good position to buy a home
A few simple questions can reveal a lot. No pressure, just clarity to guide your journey.
- No Credit Pull
- Takes 3 Minutes
- Instant Results
stay ahead of the curve
join my vip refi list
be the first to know when rates drop
FAQ
we've got the answers you need.
Didn't find your answer? Reach out to us, we're happy to help.
Book a callHow do I qualify for a loan?
Qualifying for a loan depends on several factors including your credit score, income, employment history, and debt-to-income ratio. We evaluate these factors to determine your eligibility and the best loan options for you.
How can I improve my chances of getting approved for a loan?
Improving your credit score, reducing existing debts, and ensuring a stable income can enhance your loan approval chances. We can provide personalized advice based on your financial situation. The best way to set yourself up for success is to get pre-approved early so we can look at your situation and give you a plan custom fit to your needs.
Do I need 20% down to buy a home?
No, you do not need 20% down to buy a home. There are loan programs available that allow for lower down payments, even as little as 3% down for qualified buyers. When you put less than 20% down you will have what is called PMI (private mortgage insurance). PMI is an amazing tool for homebuyers and is not something to be afraid of. We can help you explore these options based on your financial situation.
Can I get a loan if I have low credit?
Yes, it's possible to get a loan with low credit, though the options and interest rates may vary compared to those with higher credit scores. We offer a range of products that cater to different credit profiles and can provide guidance on how to improve your credit to qualify for better terms.
What is PMI, and is it bad?
PMI, or Private Mortgage Insurance, is a type of insurance that lenders require from borrowers who put down less than 20% on a home purchase. It protects the lender in case of default. PMI is not a bad thing; in fact, it is a very powerful homebuying tool. With decent credit PMI could be very cheap and allows buyers who cannot afford a 20% down payment to still purchase a home.